Where KYC fits into a Spinsy account
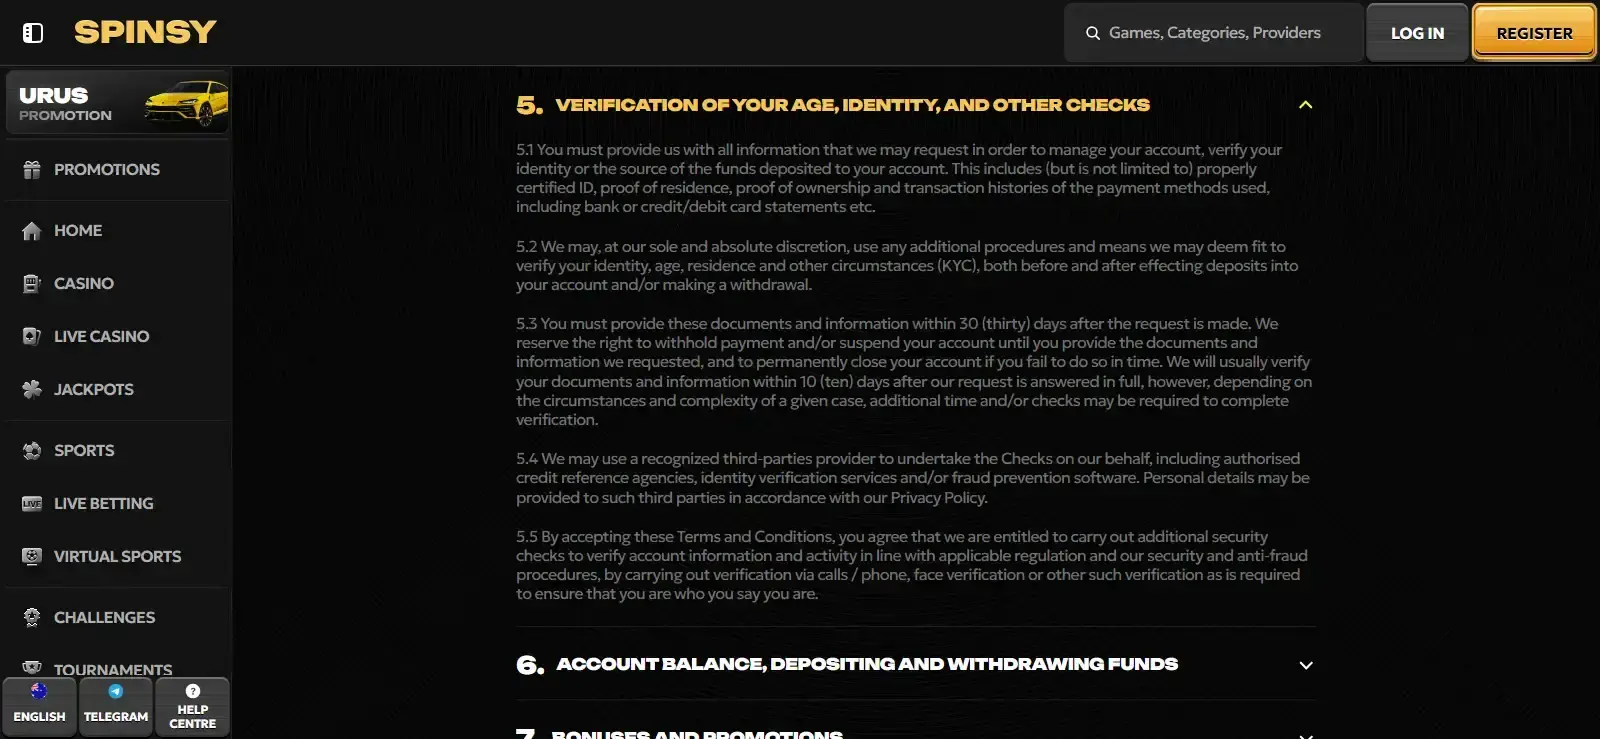
Verification is not limited to registration. The current Terms allow Spinsy to run KYC checks before and after deposits and in connection with withdrawals. That means an account can be created and used, then later receive a request for identity, residence, payment or source-of-funds information when the operator decides more evidence is required.
This is why the Spinsy account guide treats registration and verification as separate stages. Registration establishes the account under the site’s age, personal-data and duplicate-account rules. KYC is the later evidence-checking process that can be triggered around account management and deposits or withdrawals.
For wider product context, the full Spinsy Australia review separates account verification from bonuses, games, payments and mobile access. Australian readers should also keep this process separate from local regulatory approval. KYC is an operator account-control process. It does not mean Spinsy is licensed in Australia, and it is not an Australian-government verification program. The separate Australian legal status and licence guide covers that regulatory question.
What documents and evidence can Spinsy request?
The current Spinsy Terms provide a specific but open-ended list. They say customers must provide information requested to manage the account, verify identity or verify the source of funds. The examples expressly named are properly certified identification, proof of residence, proof of ownership of payment methods, and transaction histories for the payment methods used, including bank or credit/debit card statements.
The important qualification is that this is a list of possible evidence, not a promise that every account will receive the same checklist. The Terms use request-based language. A customer should therefore follow the actual request shown for the account instead of assuming that every category below must always be uploaded.
| Evidence category | What the Terms expressly name | What it is intended to establish |
|---|---|---|
| Identity | Properly certified ID | That the account holder’s identity can be verified |
| Residence | Proof of residence | That the residence information associated with the account can be checked |
| Payment ownership | Proof of ownership of payment methods used | That the customer controls the funding or withdrawal method connected to the account |
| Payment history | Transaction histories, including bank or credit/debit card statements | That account and payment activity can be matched to the requested review |
| Source of funds | Information requested to verify the source of deposited funds | That the operator can complete the source-of-funds check described in the Terms |
This page does not add passports, utility bills, selfies or other common casino-KYC items as guaranteed Spinsy requirements because the current Terms do not establish those as a universal document set for every account. The practical rule is narrower: provide the evidence actually requested through the official account process and make sure the submission is complete.
The 30-day deadline and the usual 10-day review are different
Spinsy’s Terms contain two timing statements that are easy to confuse. First, requested documents and information must be provided within 30 days after the request is made. The Terms allow the operator to withhold payment or suspend an account while requested material is outstanding, and they reserve the right to close an account permanently if the required information is not provided in time.
Second, once the request has been answered in full, the Terms say the documents and information are usually verified within 10 days. That is not an absolute completion guarantee. The same clause says additional time or checks can be required depending on the circumstances and complexity of the case.
Read the timing in sequence
Request received -> customer supplies the requested information within 30 days -> the response is complete -> Spinsy usually verifies it within 10 days -> a more complex case can take longer.
The most useful date to record is therefore not only when the first KYC message arrived, but also when the final requested item was submitted. If a document was missing or had to be replaced, the account may not yet have reached the point that the operator regards as a complete response.
Why verification can hold up a withdrawal
KYC and cashout timing intersect directly. The Terms allow verification around a withdrawal and allow payment to be withheld while requested checks remain incomplete. Separately, Spinsy’s withdrawal Terms state that the finance team works withdrawal requests within three business days when the relevant conditions and checks are complete.
That means a withdrawal with an open KYC request is not in the same state as a withdrawal that has already cleared account checks. The three-business-day finance wording should not be read as overriding a pending verification request. The dedicated withdrawal process guide explains the finance-stage timing and the distinction between internal handling and later payment-provider transfer time.
If a withdrawal appears delayed, keep the chronology separate: withdrawal request date, verification request date, date each requested item was supplied, date the submission became complete, and any later status change. That record makes it much easier to determine whether the account is waiting on customer evidence, operator review or the payment stage.
Payment ownership and transaction history are part of the official KYC scope
One detail that generic identity-only checklists often miss is that Spinsy’s Terms specifically mention payment-method ownership and transaction histories. This connects KYC to the account’s money flow rather than treating it as a simple name-and-address check.
If the account has used a payment method that the operator asks about, the relevant request may focus on showing ownership or providing the transaction history connected to that method. The Terms also allow requests related to source of funds. The public wording does not establish a single document pack that satisfies every situation, so a customer should not upload extra financial material that was not requested merely to try to speed up the review.
Use the official upload or support process specified for the account and avoid sending sensitive identity or financial documents to unofficial addresses, social-media accounts or third-party “verification” services. This is practical account-security guidance rather than an additional Spinsy document requirement.
What a complete response means in practice
The 10-day wording begins after the request is answered in full. In practical terms, the first goal is not to submit something quickly but to satisfy the exact request completely. If the operator asks for evidence from more than one category, sending only one item can leave the request open.
Before submitting, compare the request against the files prepared for the account. Check that the evidence is readable, corresponds to the account holder and payment method being reviewed, and covers the information the request actually asks for. The Terms do not provide a universal file-format specification in the facts approved for this page, so this guide does not invent one.
After submission, save the confirmation or status shown by the official interface. If support later says the response is incomplete, ask which requested item remains outstanding and keep the answer with the case record. That is more useful than repeatedly uploading unrelated documents.
A practical preparation checklist for Spinsy verification
If the account has not yet been created, the registration requirements guide covers the earlier eligibility and account-data rules. It is better to enter accurate account information from the start than to create avoidable mismatches that later need explanation.
What to ask support when verification is still open
A useful support message is specific. State when the KYC request arrived, when the requested information was supplied, and whether the interface shows the case as submitted, pending or incomplete. If the review has moved beyond the usual timing described in the Terms, ask whether the response is considered complete and whether additional information is required.
Avoid asking support to guarantee a completion date. The Terms expressly allow more time or additional checks in complex cases, so the accurate question is what stage the review has reached and whether anything remains outstanding from the customer.
Keep copies of replies and do not send passwords or one-time login codes. If a payment is also pending, maintain one chronology for the verification case and one for the withdrawal request so the two processes can be compared without mixing their dates.
How Spinsy KYC can affect the timing of an AUD withdrawal
The main timing risk is not the existence of KYC by itself but an unresolved request when a withdrawal is being processed. Spinsy can request evidence around deposits and withdrawals, and its payment terms make completed checks a condition of the stated finance-team handling window. A customer who receives a KYC request should therefore treat the document deadline and the withdrawal timeline as connected but distinct.
The cleanest workflow is to answer the exact request fully, keep proof of when it was completed, and then track the withdrawal once the account checks are cleared. The Terms give the customer 30 days to provide requested information and say a complete response is usually verified within 10 days, while also allowing longer checks in more complex cases. Those limits are useful reference points, but they are not a promise that every account will receive the same documents or finish verification on the same day.